Freelance Invoice Excel – Free Template (2026)
7
Free download
Download a charity cash working record in Excel with category summaries, restricted and unrestricted movements, and separate opening fund balances.
Use this charity accounts Excel template as an internal working record of receipts, payments and the movement of restricted and unrestricted cash. It includes ten entry rows, category summaries and a trustee-facing dashboard with separate opening balances by fund type. The example charity and all figures are fictional.
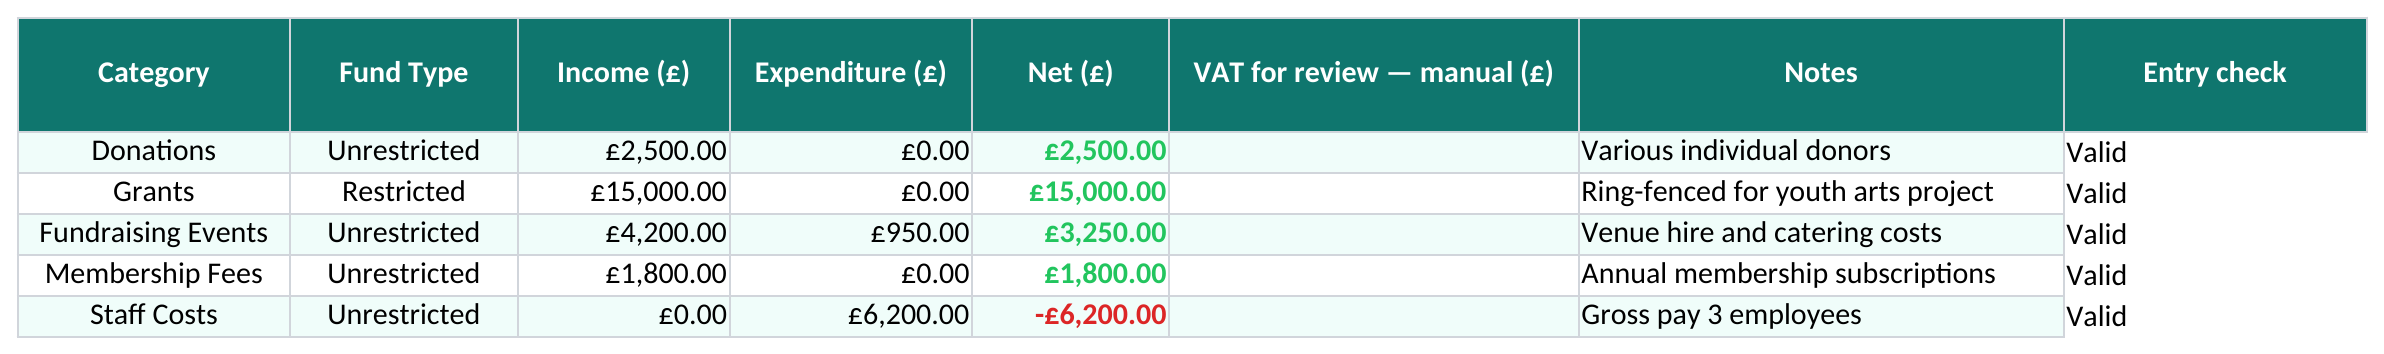
The sheet named Income & Expenditure is used here as a simple cash working record: enter actual receipts and payments for one defined period. It does not include accruals, a statement of assets and liabilities, a complete statement of financial activities or the disclosures needed for statutory accounts.
Before using the figures for annual reporting, establish the accounting basis and format required for your charity’s legal form and regulator. The Charity Commission’s CC16 receipts and payments template applies to England and Wales and includes more than a transaction list. This download is not a substitute for that complete reporting package.
Use rows 4–13 for the date, description, category, fund type, income and expenditure. Enter zero in the unused amount column. If an event line includes both receipts and payments, retain a supporting breakdown and keep the two figures separate; entering only a net event surplus would hide the gross activity.
| Field | What to enter | What the workbook does |
|---|---|---|
| Category | A consistent activity or cost label | Groups the named categories |
| Fund Type | Restricted or Unrestricted | Separates the two groups in the summary |
| Income and Expenditure | Actual cash received and paid | Calculates movement as receipts minus payments |
| VAT for review | An amount checked separately, if relevant | Keeps it as a manual note; does not infer recovery |
| Entry check | Calculated from the required inputs | Flags incomplete dates, amounts or fund types |
Totals exclude flagged entries. The dashboard keeps closing cash blank until the flagged rows are resolved, so a missing amount cannot quietly produce a complete-looking closing figure. Keep the receipts, bank references and other evidence behind every line.
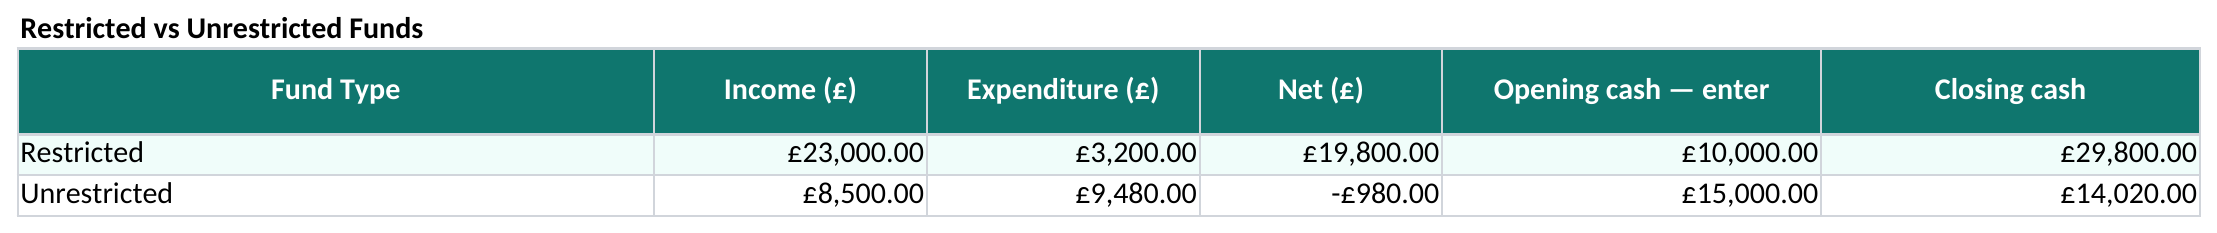
Enter opening restricted cash in Dashboard!E13 and opening unrestricted cash in E14. Each closing figure is opening cash plus that group’s receipts minus its payments. The combined closing cash is the sum of those two figures.
The fictional restricted example starts with £10,000, receives £23,000 and pays £3,200, giving £29,800 closing cash. That arithmetic does not establish that all payments satisfy the donor’s conditions; the supporting fund records still need review.
This file groups all restricted activity together. It does not track each individual restricted fund, endowment or transfer between funds. The Charity Commission’s internal financial controls guidance explains the need for accounts to reflect separate restricted and endowment funds. Keep that detailed ledger alongside this summary.
A trustee designation of unrestricted money is different from a restriction attached to donated funds. Also, cash held is not automatically free reserves. Consult the Commission’s reserves guidance when preparing a reserves figure or policy.
The earlier automatic “VAT reclaimable” calculation has been removed. An Office Costs category does not establish whether VAT was charged or whether any recovery is available. Column H is now a manual amount for review and does not affect the cash movement or calculate a claim.
This compact version has ten entry rows. To add more, extend the transaction area and every dependent total, category summary, fund summary, validation and dashboard reference together. Do not overwrite the totals on row 14 or the summaries below them.
Before handing figures to the treasurer, examiner or accountant, resolve entry flags, reconcile cash with the underlying records, confirm each fund’s opening position and retain the supporting breakdowns. For a committee-level narrative accompanying the figures, see the club treasurer report template.
No. It is an internal working record. The required annual accounts depend on the charity’s legal form, accounting basis and regulator; additional statements, reports and disclosures may be needed.
No. It groups records into Restricted and Unrestricted. Keep a separate fund ledger for each restriction and use the workbook only as a summary.
A cost category does not determine VAT treatment or entitlement to recovery. The revised file records a separately checked amount without presenting it as automatically reclaimable.
They are cash balances for the two fund groups. They are not automatically free reserves or a complete balance sheet.
Excel template by
Guide written by